When an Uber driver causes a serious crash, injured people often ask whether the driver, Uber, or an insurer will pay. The answer depends on the driver’s app status, the person who caused the collision, policy limits, and the losses claimed. Coverage changes based on whether the driver is waiting for requests, has accepted a trip, or is carrying a passenger. These distinctions explain which insurer receives the claim and why.
Which Insurance Policy Responds?
An injured person should treat the crash as an insurance claim involving several possible payers. The driver’s status in the Uber app determines which policy responds, while state law controls coverage details and liability standards. A Miami Uber accident lawyer can identify the insurer, preserve evidence, and calculate damages before a recorded statement weakens the claim. This review matters when injuries require surgery or long-term care.
- Commercial Liability Coverage
Uber maintains commercial liability coverage for drivers who accept a ride request, travel to pick up a passenger, or carry a passenger. The company states that this coverage generally includes at least $1 million for injuries and property damage during those stages. Coverage terms and limits still vary by state and the driver’s exact activity.
- When the Driver Has Not Accepted a Request
A different rule applies when the driver is online but has not accepted a request. Uber lists lower third-party liability limits for that period, including $50,000 per person, $100,000 per accident, and $25,000 for property damage. When the driver is offline, the personal auto policy usually applies, subject to its terms and exclusions.
Who Pays for the Injuries?
The at-fault driver’s liability insurer usually becomes the first source of payment. A claim can include reasonable medical expenses, lost income, reduced future earning ability, property damage, and compensation for physical pain. A serious injury claim requires records that connect each loss to the collision.
- When Another Driver Causes the Crash
If another motorist caused the crash, that motorist’s insurer usually handles the claim instead. A rideshare passenger, pedestrian, or driver can sometimes pursue uninsured or underinsured motorist coverage through a personal policy or available rideshare coverage. These benefits vary by state and policy language.
- Why Policy Limits Are Important
Policy limits become a serious issue when injuries involve extended treatment or permanent impairment. A settlement that reaches the available limit might still leave losses unpaid. The injured person can examine other applicable policies and pursue the responsible driver personally, although collection depends on available assets.
Is Uber Personally Responsible?
Uber’s insurance can pay a covered claim without making Uber the negligent party. Whether the company faces direct liability depends on state law, the driver’s legal relationship with Uber, and facts involving hiring, supervision, vehicle ownership, or conduct connected to the crash.
The driver remains a central party because that person’s driving caused the collision. Investigators examine speed, traffic signals, distraction, impairment, road conditions, and the driver’s decisions immediately before impact. The company’s role in the insurance arrangement does not remove the need to prove fault and damages.
See also: Publishing on Demand: A Modern Approach to Bringing Your Ideas to Life
Evidence That Determines Payment
Evidence often determines which insurer accepts responsibility. Important records include the police report, photographs, medical files, witness contact details, vehicle damage, traffic camera footage, and the trip receipt.
The Uber app can establish whether the driver was offline, waiting for a request, traveling to a pickup, or carrying a passenger. Trip data can also identify the route, timing, and people connected with the ride. A written preservation request can protect records that could later disappear.
Medical treatment should begin promptly, even when pain appears manageable. Delayed treatment gives an insurer the chance to argue that symptoms came from another cause. Consistent medical records connect the injury, treatment, restrictions, and financial losses.
Steps After a Serious Crash
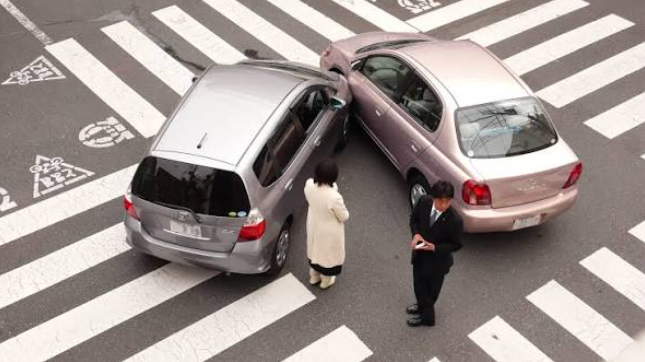
Call 911, request medical assistance, and provide accurate information to the responding officer. Do not admit fault, guess about speed, or speculate about what caused the collision. Photograph the vehicles, roadway, signs, visible injuries, and surrounding conditions if it is possible to do so safely. Collect the driver’s insurance information and witness contacts, then report the crash through the Uber app or rider support channel.
Notify the relevant insurance companies, but do not give a recorded statement before an attorney reviews the facts. An insurer can use casual comments to dispute fault or reduce the value of a claim. Legal advice becomes especially useful when injuries are severe, several vehicles are involved, or available coverage remains unclear.
Conclusion
Payment after a serious Uber crash depends on the driver’s app status, fault, policy limits, and documented losses. Uber’s commercial insurance often responds during an accepted trip, but the responsible driver’s personal policy, another motorist’s insurer, or the victim’s own coverage can matter. Injured people should preserve trip records, obtain medical care, avoid recorded speculation, and seek advice before accepting payment. A prompt claim review protects rights before evidence disappears or deadlines expire.