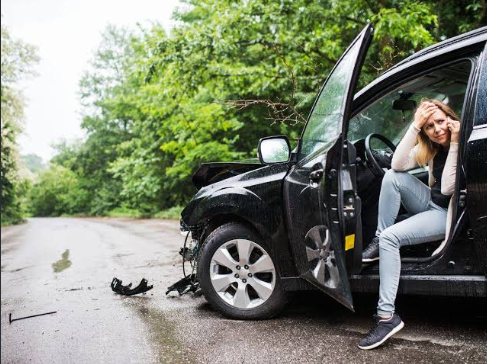
A serious accident can create financial pressure long after emergency treatment ends. Hospital charges, follow-up care, missed paychecks, vehicle repairs, and household changes can all stretch beyond available savings. Some losses are immediate, while others develop over months as injuries affect work, mobility, and emotional health. Understanding each expense helps accident victims document damages, protect their finances, and get the right advice before bills and deadlines become harder to manage.
Medical Bills After an Accident
Emergency care is often the first major expense. Ambulance transportation, emergency department treatment, imaging, surgery, hospital stays, and prescription medication can generate separate bills from different providers. Even insured patients can face deductibles, copayments, coinsurance, and uncovered services.
Treatment costs can continue after discharge. Physical therapy, specialist appointments, medical equipment, home health services, and follow-up testing can become recurring expenses. A serious injury also requires records showing the diagnosis, treatment plan, invoices, insurance payments, and remaining balances. Consulting qualified counsel like Levine and Wiss helps victims understand how to go about these steps promptly.
Mental health care also deserves attention after such a traumatic event. Anxiety, depression, sleep disruption, and post-traumatic symptoms can affect recovery and employment. People coping with depression after an accident should seek the right care. Additionally, documenting these symptoms helps connect emotional harm to the accident and supports continuity of care.
Lost Income and Reduced Earning Ability
An injured worker can lose income from missed shifts, unpaid leave, reduced hours, or a temporary inability to work. The financial impact isn’t limited to regular wages. Overtime, commissions, bonuses, tips, and self-employment revenue can also become unavailable during recovery.
A lasting injury can lead to bigger losses. Someone may return to work with restrictions, move into a lower-paying position, or leave a profession that requires physical activity. Future earning losses require careful analysis of age, education, work history, medical limitations, career path, and expected retirement timing.
Accurate documentation strengthens an income claim. Pay stubs, tax returns, employment records, schedules, benefit statements, and written work restrictions can show both past losses and ongoing limitations. Employers can also confirm missed time, modified duties, and lost opportunities.
See also: Publishing on Demand: A Modern Approach to Bringing Your Ideas to Life
Property Damage and Transportation Costs
Vehicle damage creates expenses beyond the repair estimate. Towing, storage fees, rental transportation, rideshare charges, and replacement equipment all add to the total. If a vehicle is declared a total loss, the owner must compare the insurer’s valuation with the vehicle’s actual market value before accepting payment.
Accidents can damage phones, laptops, clothing, safety equipment, tools, and other personal property. Photographs, purchase receipts, repair estimates, and replacement prices help establish those losses. People should avoid discarding damaged items before documenting them, unless keeping them is unsafe.
Transportation costs continue when an injury prevents driving. Regular trips to medical appointments can become expensive, especially for people who need specialized treatment or assistance from another person.
Household and Personal Costs
Serious injuries often change how a household functions. An injured person may need paid help with cleaning, cooking, childcare, yard work, errands, or personal care. Family members who provide unpaid assistance also lose work hours and take on extra responsibilities.
Home modifications can create another expense. After a disabling injury, ramps, bathroom supports, stair equipment, bedroom changes, and mobility devices may become necessary. Each purchase should connect to a documented medical recommendation and a clear functional need.
Financial strain can also produce additional costs. Late fees, overdraft charges, canceled services, and credit card interest often follow when income stops while bills continue. Victims should track these amounts separately, with dates and supporting statements.
How to Organize Accident-related Losses
A simple record of the accident-related losses can help injured people avoid overlooking expenses. Keep medical bills, insurance letters, wage records, receipts, repair documents, appointment logs, and notes about daily limitations in one secure location.
A written expense ledger should include the date, amount, payee, reason for payment, and related document. Separate paid amounts from unpaid balances, and record reimbursements from health, auto, or disability insurers.
People should also avoid guessing about future costs. A treating physician can explain expected care, while financial and legal professionals can assess how those needs affect income and household expenses. Early organization makes later decisions more informed.
Conclusion
A serious accident can affect nearly every part of a household budget, including expenses that do not appear on the first hospital statement. Medical care, lost wages, reduced earning ability, damaged property, transportation, home assistance, and emotional treatment require separate records. Injured people should start a dated loss file, preserve receipts and employment documents, and follow medical recommendations. A complete financial picture gives counsel better information when evaluating recovery costs and available options.